Chapter 6 - THE GLASS ROOM
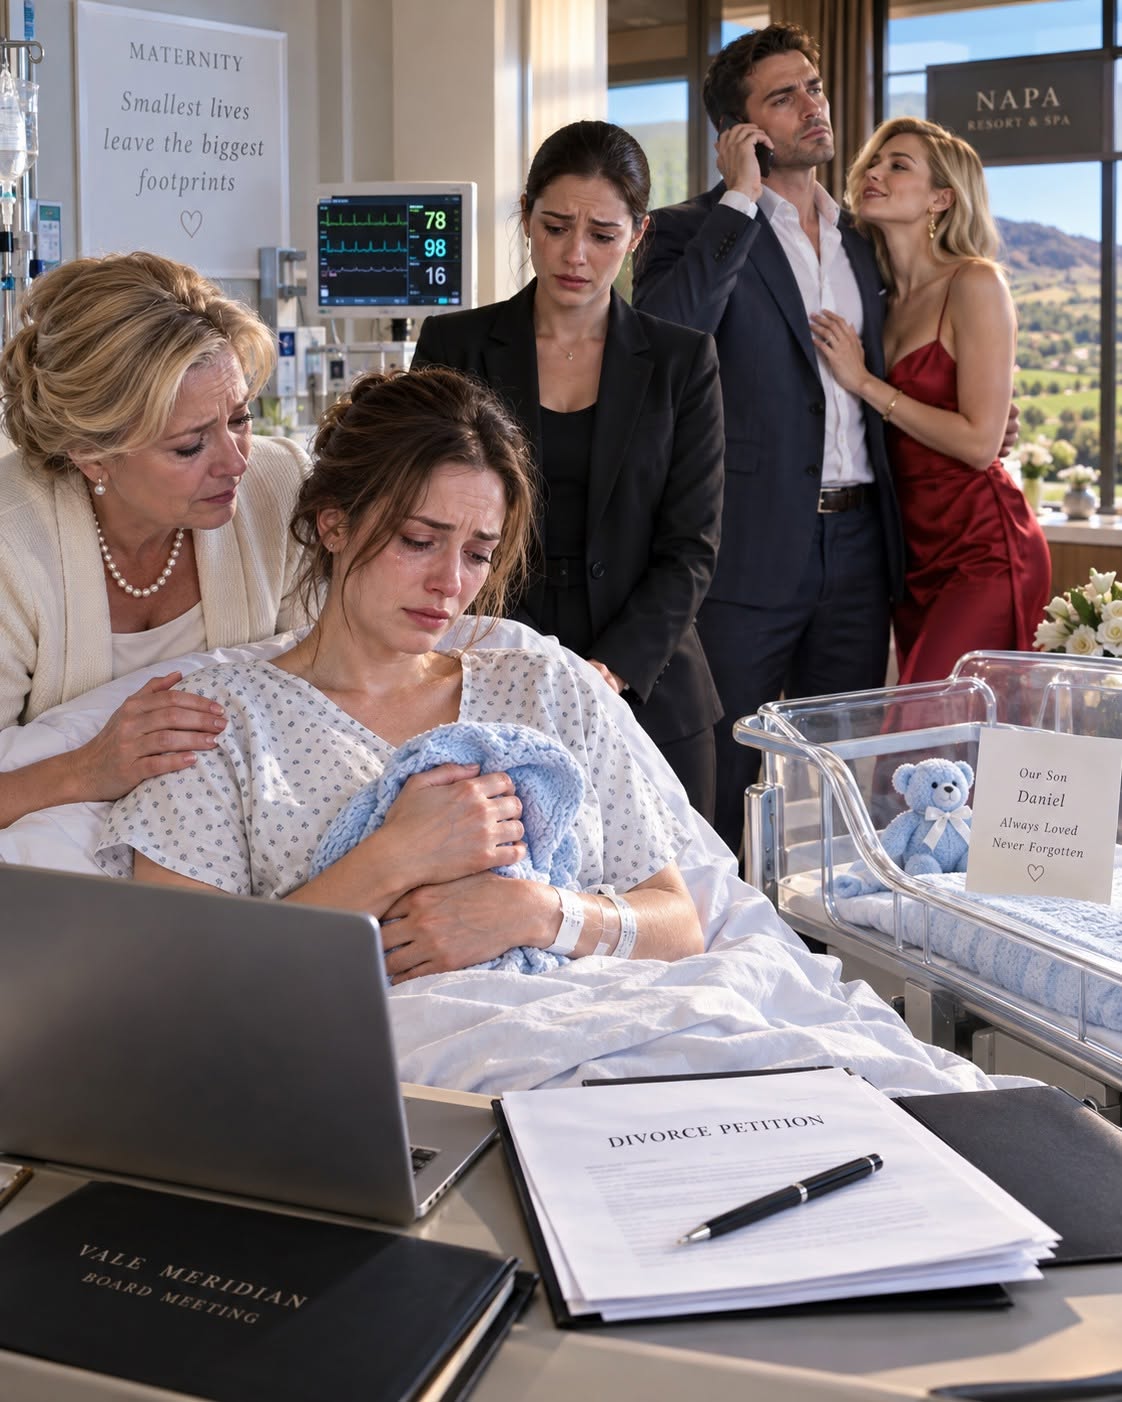
Harrington Capital gave us ten business days to respond, a deadline designed to create panic. Their offer valued Vale Meridian at nearly thirty percent above the previous quarter’s market price, enough money to make even loyal directors reconsider principles they had defended for years. Analysts called it generous. Commentators described the company as wounded after Julian’s resignation and suggested a sale might be the cleanest solution. What none of them understood was that Vale Meridian was not merely an asset to me. It was also not a shrine. My father had taught me that companies existed to serve people, not memories. If selling truly benefited employees and long-term investors, I would consider it. But I would not sell because someone mistook grief for weakness.
I convened a strategy retreat in the twentieth-floor boardroom, a glass-walled room that overlooked San Francisco Bay. Samuel, Priya, the finance team, outside advisers, and two employee representatives attended. I insisted on the employee seats because acquisition models often reduced human lives to “synergies.” Harrington’s proposal projected hundreds of millions in savings, much of it from consolidating operations. When we translated that word into jobs, the number was almost three thousand. Their plan also separated our logistics software division from the manufacturing network my father had built to support it. Financially, it might create short-term value. Strategically, it hollowed out the company and sold the pieces.
For two days we analyzed alternatives. Our chief technology officer, Elena Park, presented a plan to spin out a minority stake in the software division while keeping operational control. The cash could reduce debt and fund modernization without mass layoffs. The proposal was less dramatic than Harrington’s premium, but it had a credible path to long-term growth. I asked ruthless questions because I did not want sentimentality disguised as strategy. Elena answered each one with data. At the end of her presentation, she said something my father would have liked: “A company can be disciplined without becoming disposable.” The room went quiet. I knew then what direction I wanted to take.
Julian unexpectedly became relevant again when Harrington’s managing partner claimed their offer had been encouraged by previous leadership. Lawyers produced email threads showing Julian had indeed discussed structural options with them, though he had never authorized a sale. The revelation fueled another wave of press. Julian called Rebecca and offered to testify before the board that Harrington had exaggerated his support. I did not want to need him, but the truth mattered more than my pride. We scheduled a special session. When he entered the glass room, everyone watched him as if a ghost had walked into his old house.
Julian did not ask for his chair back. He sat at the far end of the table beside his lawyer and answered questions for nearly three hours. He admitted he had invited Harrington to explore valuation scenarios because he wanted leverage and because he feared my trust control. He denied supporting a breakup of the company and produced notes showing he rejected one early proposal involving layoffs. The testimony complicated the simple story people preferred. Julian had been secretive, disloyal, and reckless, but he had not plotted to burn Vale Meridian down for a payday. Human beings are rarely villains in every room. Accepting that did not lessen what he had done to me; it only kept me from becoming dishonest in return.
After the session, he waited by the elevator and asked if I had a minute. I almost said no. Then I noticed he was holding Daniel’s bracelet, which I had returned to him through counsel. He told me he had started therapy and joined a support group for fathers who had lost children. He said he was not telling me for forgiveness, only because he needed me to know he was trying to become someone who could live with what he had done. I wished him well. The words felt strangely peaceful. There was no anger left in them, but no invitation either.
The board rejected Harrington’s proposal unanimously the next morning after reviewing Elena’s plan and employee-impact data. We announced a restructuring centered on technology investment, debt reduction, and stronger governance. The market dropped seven percent that day because traders had expected the acquisition premium. Commentators called our choice stubborn. Harrington’s partner went on television and said family control was preventing shareholders from realizing value. I watched the interview without flinching. Short-term markets are loud; long-term consequences are quieter. We scheduled a shareholder vote to approve the spinout and new governance protections.
May you like
That evening, I stayed alone in the glass boardroom after everyone left. The city lights flickered below, and for a moment I remembered sitting there beside my father when I was sixteen, bored by a Sunday budget meeting. He had pointed at the city and told me every glowing window contained someone who depended on another person doing their job well. I had thought it was just another lecture. Now I understood. Leadership was not the ability to command a room. It was the willingness to remain responsible after the room emptied.
My phone buzzed with a message from Dr. Morgan. She had connected me with a hospital committee developing better support for families experiencing stillbirth and pregnancy loss. They were seeking donors for private rooms away from the general maternity wing. I stared at the message for a long time. The memory of waking beside an empty bassinet still had the power to stop my breathing. I could not change what happened to Daniel, but perhaps I could change one detail for the next woman who woke into that silence. I wrote back that I wanted to meet. Outside the glass walls, Vale Meridian’s future remained uncertain, the shareholder vote still weeks away. Yet for the first time since the hospital, I felt I was moving toward something rather than merely away.