Chapter 3 - THE ACCOUNT THEY COULDN’T REACH
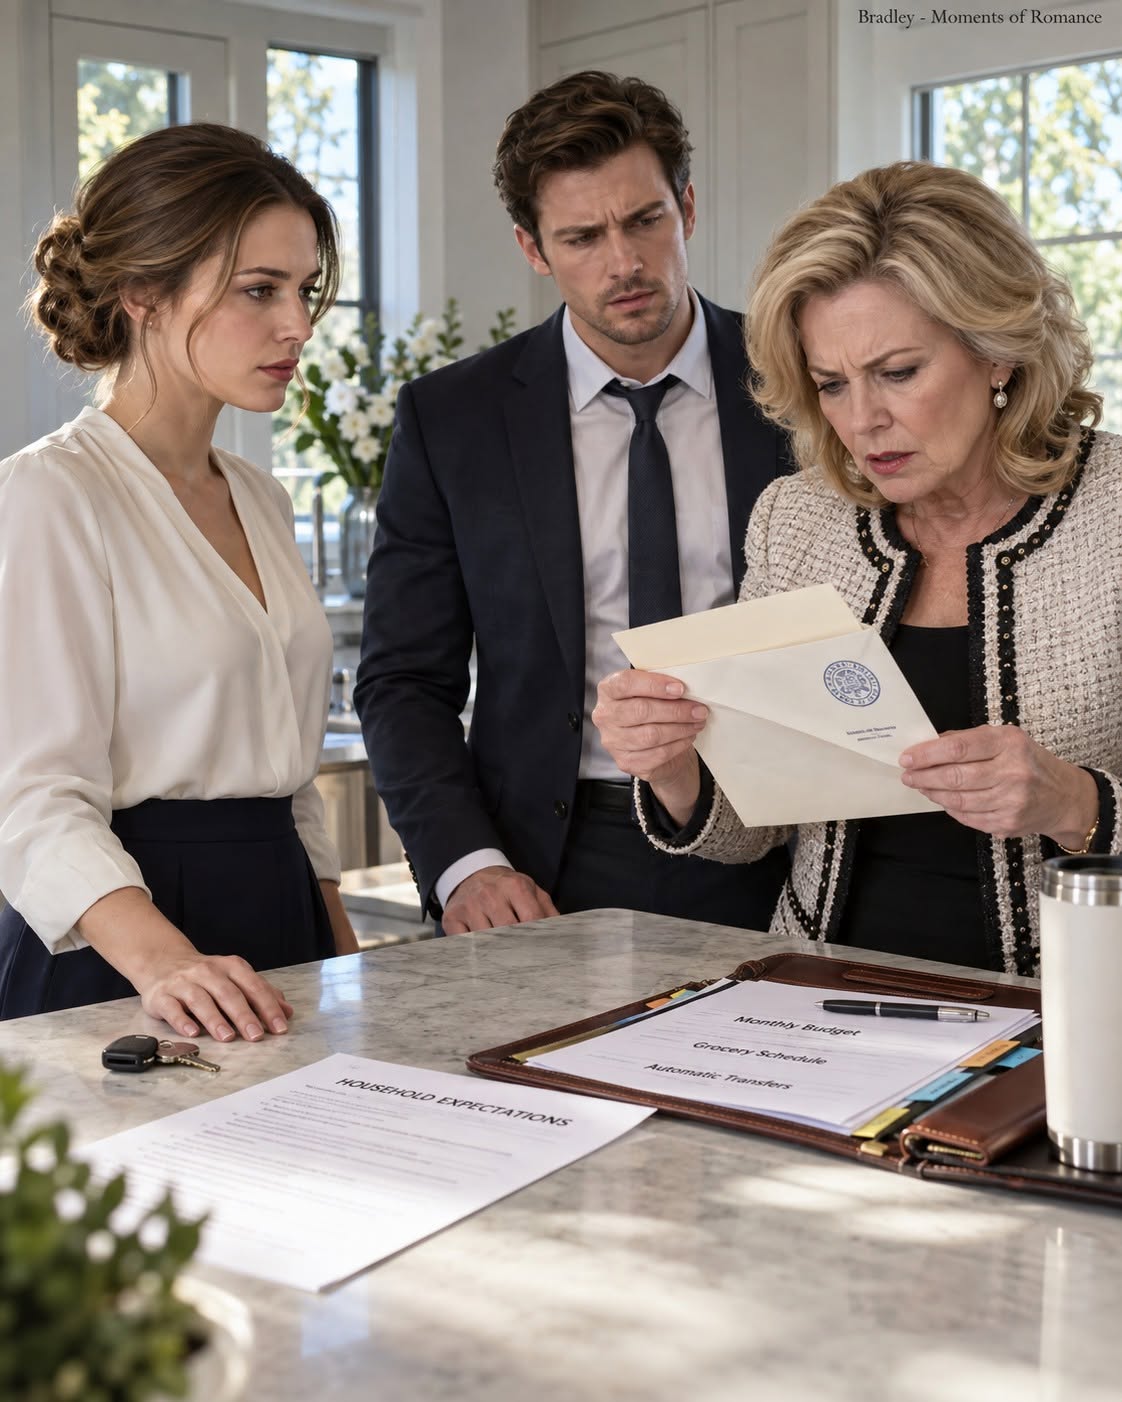
At nine that morning, I sat across from Melissa Grant in a conference room that smelled faintly of coffee and printer toner. The city outside her windows was beginning its ordinary weekday rhythm—delivery trucks, office workers, buses braking at the corner—while my six-day marriage seemed to be collapsing in fast motion. Melissa arranged my screenshots, photographs, and certified documents into separate stacks. She did not dramatize what she saw. That steadiness helped more than sympathy would have.
“First,” she said, “we separate what feels outrageous from what is legally actionable.” She pointed to Heath’s Household Expectations sheet. “Controlling and deeply concerning, but not a contract because you did not sign it. The account-link request is more serious. The proposed home-equity plan is serious if they took steps beyond discussion. And if Heath told a lender he owned the house, that could create an entirely different problem.” I appreciated that she refused to promise a cinematic courtroom victory. She dealt in records, dates, signatures, and things that could be proven.
We called my credit union together. The security officer confirmed that someone with access to enough of my personal information had initiated a request to link my checking account to a newly opened joint account. The request had not completed because a verification code had been sent only to my device. I changed my passwords, replaced security questions, added a verbal password, froze external transfers, and placed alerts on every account I owned. Then I contacted the three major credit bureaus and froze my credit.
By noon, my hands had stopped shaking. Fear becomes different when you give it tasks. Melissa drafted a letter requiring Heath to preserve all communications and financial records related to my property. She also prepared formal notice under the occupancy addendum, carefully following the process required in our county. I was not going home to toss his clothes onto the lawn. I was going home with a plan, because the law was not a weapon to swing in anger. It was a structure, and structure was exactly what Heath had tried to take from me.
When I returned, Heath was sitting in the living room with the curtains closed. The Household Expectations sheet had disappeared from the island, but he had left behind the faint rectangle of coffee where Rhonda’s binder had rested. He looked exhausted, though it was barely one in the afternoon. “Mom overreacted,” he said before I had set down my bag. “The debt numbers were worst-case projections.” I asked whether he had spoken to a lender about my house. He looked at the floor.
Finally he admitted that he had met with a loan officer two days after our wedding. He said he had only wanted to “see what was possible.” He had told the officer that he was recently married and living in the property, then implied he expected to be added to the title. According to him, the loan officer had requested documentation before proceeding. He claimed nothing had been submitted. I asked for the name of the lender. He refused.
That refusal told me I still did not know enough. I handed him Melissa’s preservation letter and notice. He read the first page, then threw it onto the coffee table. “You lawyered up against your husband.” I sat across from him and kept my voice even. “My husband tried to link my bank account without permission and discussed borrowing against a house he doesn’t own.” He shook his head as if my phrasing were the betrayal. “I was trying to fix things for us.”
“For us?” I asked. “What debt did I create?” He flinched. Then the story began to change. The forty-two-thousand-dollar business line belonged to Rhonda’s home-staging company, which had been losing clients for over a year. The twenty-eight-thousand-dollar personal loan was Heath’s. He had taken it out to invest in a friend’s restaurant expansion that failed before opening. The credit cards were a mixture of his spending and cash advances he had used to help his mother make payroll.
I felt anger, but beneath it was grief. None of those choices alone would necessarily have ended us. Debt could be dealt with. Business failures happened. People made foolish investments and recovered. What changed everything was the decision to hide it, marry me, and then treat my savings and home as a private rescue fund. “Why didn’t you tell me before the wedding?” I asked. Heath gave me an answer so revealing I would hear it in my head for months.
“Because you would have wanted to delay things.” He said it almost quietly. He had known honesty might change my decision, so he removed honesty from the process. I sat there staring at the man I had married and understood that manipulation did not always look like shouting or threats. Sometimes it looked like withheld information arranged carefully around your consent.
That evening, Rhonda began calling. I ignored the first three calls and saved the voicemails. In one, she said marriages required sacrifice. In another, she accused me of humiliating Heath by involving an attorney. In the third, her tone softened and she said she had always thought of me as a daughter. Ten minutes later, she texted that I was selfish for protecting “dead equity” while family members were drowning.
I forwarded everything to Melissa. Heath watched me from the doorway. “Do you really need to document every sentence?” he asked. “Yes,” I said. He laughed bitterly. “Of course. That’s what you do. You turn life into paperwork.” I almost reminded him that paperwork was the only reason he had not already found a way to reach my home equity. Instead, I went upstairs and locked the fireproof drawer for the first time since we married.
At 8:43 p.m., an email arrived from a mortgage brokerage I did not recognize. The subject line read: ACTION REQUIRED — OWNERSHIP DOCUMENTATION. My pulse jumped. The message thanked “Mr. and Mrs. Mercer” for their interest in a home-equity consolidation product and requested a current deed, insurance declaration page, and authorization to verify income. Attached was a preliminary application. I opened it carefully.
My name was on the form. So was my address. My estimated income was close enough to be disturbing. Under property ownership, a box had been checked beside JOINTLY OWNED. The form had not been completed, and there was no signature from me. But Heath’s email address appeared in the contact field. I looked across the bedroom toward the hall, where I could hear him opening a cabinet downstairs.
May you like
I forwarded the email to Melissa and the lender’s compliance department with three sentences: I did not authorize this application. I do not jointly own this property. Please preserve all records related to this inquiry. Then I closed my laptop and sat very still. Until that moment, some part of me had continued searching for an explanation in which Heath was merely foolish, pressured by his mother, or desperate.
The application ended that search. He had not simply imagined using my money. He had started building the road to reach it.