Chapter 4 - THE HIDDEN TAB
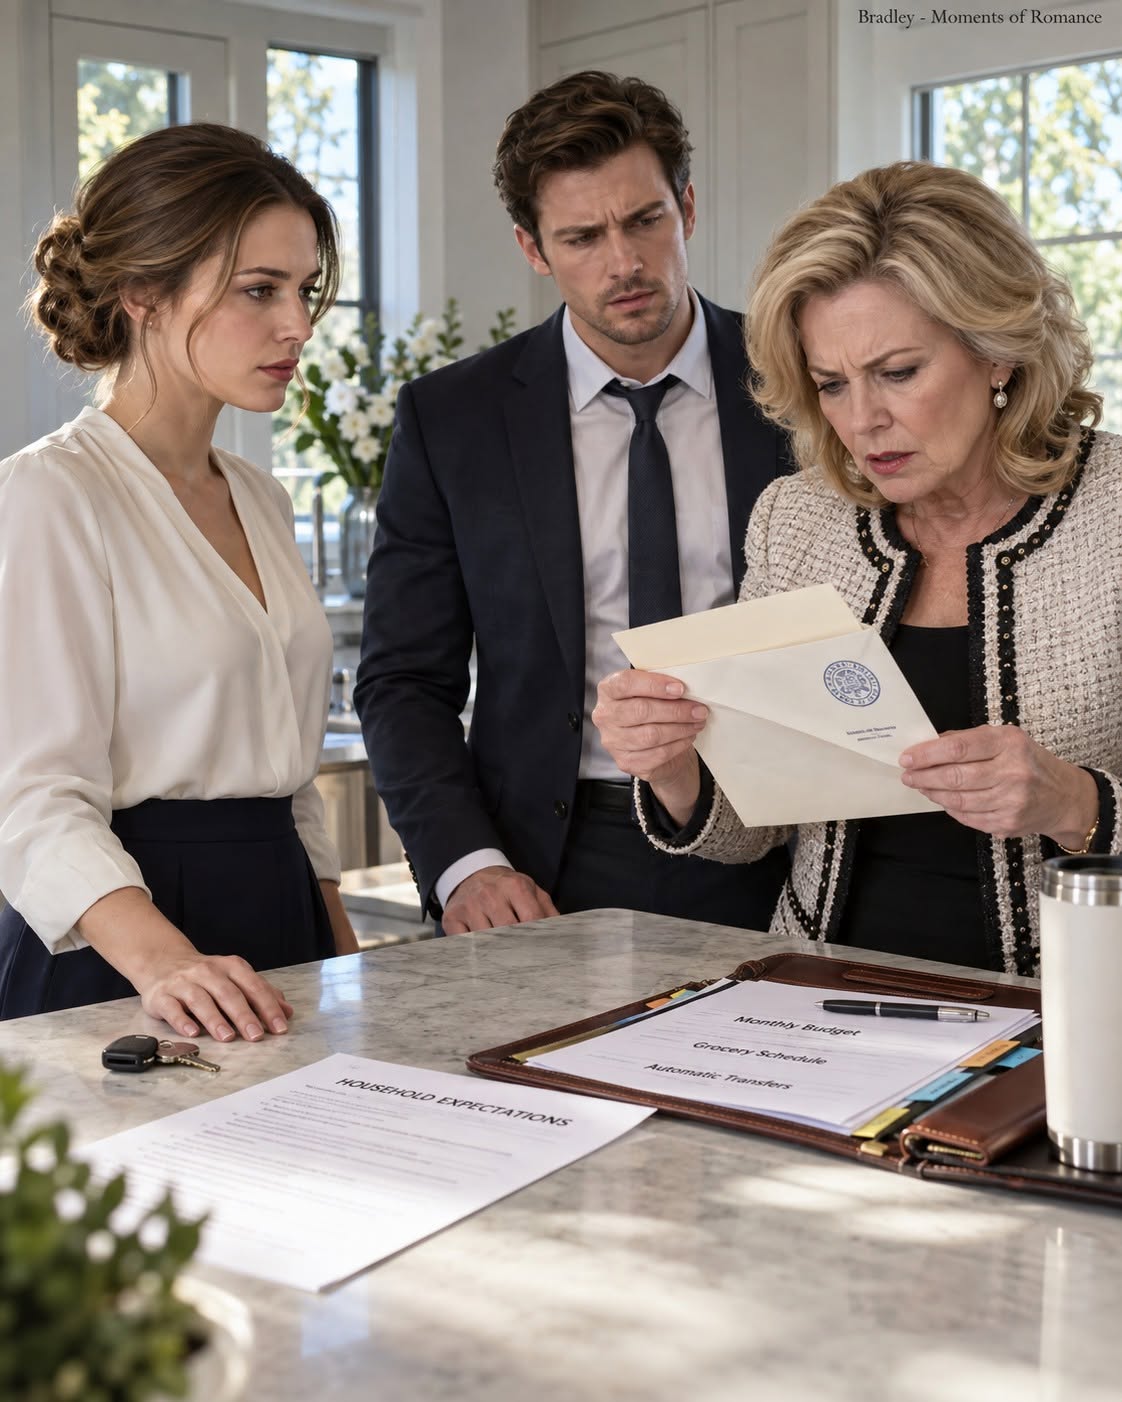
The mortgage company called me at 8:07 the next morning. A compliance manager named Dana Ruiz spoke carefully, asking me to verify my identity before discussing anything. She confirmed that an online inquiry had been created from Heath’s email address and followed by a phone conversation with a loan representative. No loan had been approved, no lien had been placed, and no funds had moved. But notes in the file showed that Heath described the property as “marital residence, expected joint ownership” and said title documents would follow.
Dana told me the company would freeze the inquiry and preserve the file. She could not tell me what conclusions their internal review might reach, but she assured me that no application using my property would proceed without verified ownership and my consent. I thanked her, wrote down the case number, and felt the strange combination of relief and nausea that comes when you learn a locked door really did stop someone who had already tried the handle.
Heath came downstairs while I was still on the call. I did not hide what I was doing. When I repeated the case number to Dana, his face changed. “You contacted them?” he demanded after I hung up. I looked at him. “They contacted me.” He began saying it was a misunderstanding, that the loan officer had filled out the form incorrectly, that “expected joint ownership” was not the same as claiming he currently owned the house. Each explanation arrived faster than the one before it.
Then he made his biggest mistake. “Mom said they wouldn’t care once your name was on the final authorization anyway.” The room went silent. Heath seemed to hear his own sentence a second too late. “What final authorization?” I asked. He turned away. I followed him into the kitchen, where sunlight was pouring through the windows onto the same island that had held Rhonda’s binder. “What did you think I was going to sign yesterday morning?”
He said nothing. I remembered the three clipped forms Rhonda had brought, the ones she gathered after the envelope changed everything. One had been labeled automatic transfers. I had only photographed the consolidation worksheet. In the rush of the confrontation, I had not captured every page. “Call your mother,” I said. Heath refused. I told him I already knew enough to involve the lender’s compliance department and my attorney, and that hiding more would only make the record worse.
He sat down slowly. “There was a financial authorization.” My stomach tightened. The form, he explained, would have allowed joint management of certain accounts. He insisted it did not directly authorize a home-equity loan. But Rhonda had planned to use the appearance of unified finances to support a broader consolidation package. “She thought once everything looked shared, you’d stop being so territorial,” he muttered.
Territorial. About my own house. My own bank account. My own paycheck. The word was so absurd that I nearly laughed, but there was nothing funny left. I went to the upstairs guest room, closed the door, and began searching the shared wedding-planning tablet we had both used for vendors. I was not digging through a private device; it was a household tablet signed into a shared email account. Still, I moved carefully, looking only for messages related to finances and the mortgage inquiry.
I found them in a folder Heath had named “After Wedding.” The folder contained receipts, a honeymoon itinerary, and a PDF called PHASE TWO. My breath caught. The document was not from a bank. It was a spreadsheet Rhonda had created. At the top were four dates: wedding, account merge, title discussion, consolidation. Under “title discussion,” she had written, “Do not push immediately. Establish routine first.” Under “account merge,” she had listed my paycheck, savings balance estimate, and monthly mortgage payment.
The figure beside my savings was wrong by more than ten thousand dollars, which meant they had been estimating rather than viewing the account. That should have comforted me. Instead, it made the planning feel more deliberate. Under “consolidation,” Rhonda had written “business LOC + H personal + cards,” followed by the proposed $110,000 HELOC. A final note read, “Once pressure is off, rebuild together.”
I photographed the screen and sent the file to myself, then to Melissa. My hands were icy. There it was, a timeline for turning marriage into access. They had not needed to forge my signature if they could pressure me into providing one. That was why the Household Expectations sheet mattered. It was not merely insulting domestic nonsense. It was step one: establish control, normalize permission, redirect income, reduce my outside commitments, and make every financial choice subject to their approval.
The evening classes suddenly made sense too. Three nights a week, I taught women and men how to recognize financial coercion. Heath had called those classes inconvenient. Rhonda had called them unnecessary. Maybe they had not consciously feared what I taught. Maybe they had simply resented any place where I had independence, colleagues, and people who knew what I did. Either way, the result was the same.
When Heath found me in the guest room, I had the PHASE TWO spreadsheet open. He stopped in the doorway. “Where did you get that?” I told him it was in our shared account. His face drained. For a few seconds, anger disappeared and something younger took its place—shame, perhaps, or the realization that denial had become impossible. “Mom made that,” he said.
“Did you know about it?” I asked. He hesitated. “Some of it.” I pointed to the line about account merging. “Did you know about that?” Yes. “The title discussion?” Yes. “The HELOC?” He looked away. That was also yes. I closed the tablet.
Heath began talking about pressure. Rhonda’s business was close to failing. She had mortgaged her condo years earlier to help him through college and later co-signed his failed restaurant investment. He said he felt responsible. When he learned how much equity I had in the house, he saw a solution that could “save everyone.” He insisted he never meant to take anything permanently. The plan, in his mind, was to borrow, stabilize the debts, and repay the line together.
“Together,” I repeated. “With my property securing your secret debts.” His eyes filled, but I did not feel victorious. This was the man whose hand I had held at our wedding, whose socks were still mixed with mine in the laundry basket upstairs. I wanted the truth to make him recognizable again. Instead, every truth moved him farther away.
That afternoon, Melissa called after reviewing the spreadsheet. She told me to preserve the shared tablet exactly as it was and not delete or edit anything. She also said something I had been avoiding. “Mara, you need to decide whether you feel emotionally and physically safe sharing the house while this is unfolding.” Heath had never hit me. He had never threatened violence. But safety was larger than that now. It included access, pressure, passwords, documents, and the possibility that desperation might push him toward choices I could not predict.
I asked Heath to stay with a friend until we could meet with attorneys. He refused at first, saying it was his marital home. I reminded him the occupancy notice had already been served and that I was not asking him to vanish without process. I was asking for space. He packed one bag before midnight and left for his friend Caleb’s apartment. At the door, he turned and said, “You know my mother is going to lose everything.”
May you like
I looked at him for a long moment. “Then she needs a plan for what belongs to her,” I said, “not one built around what belongs to me.” He left without answering. When the door closed, I slid the deadbolt into place and leaned my forehead against the wood.
For the first time since the wedding, the house was quiet enough for me to hear my own thoughts.